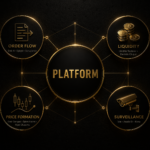
In the previous article, the scope of activities that platforms may carry out was examined. In this section, the focus shifts to how these activities operate within the market. Articles 10 to 13 of the Communiqué do not merely define platforms; they set out how transaction flows are constructed, how orders are matched, where price formation occurs, and how liquidity is consolidated.
When read together, these provisions reveal a clear structure: orders, execution, price formation, and surveillance are concentrated within a single centre. The transaction flow circulates within the platform, and the market operates through this structure.
Although Articles 10 to 13 of Communiqué No. III-35/B.2 may, at first glance, appear to regulate a technical transaction flow, a closer reading demonstrates that these provisions point to a far more comprehensive market architecture. The regulation does not confine itself to describing the lifecycle of an order from entry to execution; it also determines where, how, and within which structure this process takes place.
Within this framework, an order is accepted by the platform, matched within the same structure, executed, and the balance is updated. The entire process remains within the platform. The fact that orders are not routed to external markets leads to the aggregation of liquidity within the same system and to the formation of order book depth at that centre. In this way, the transaction flow is not fragmented; rather, it gains coherence by concentrating within a single centre.
Within this structure, the platform is not limited to a classical intermediation function. It aggregates order flow, manages the matching process, monitors executed transactions, and, where deemed necessary, directly intervenes in the process. The convergence of the trading environment and the surveillance function within the same system transforms the platform from a mere technical infrastructure provider into an active element shaping market operation.
Indeed, the regulation does not merely assign the platform an organisational role. In addition to core functions such as maintaining the order book, executing matching, and finalising transactions, it also allows the platform, in certain circumstances, to act as a counterparty to transactions. In this respect, the platform goes beyond being a channel through which transactions pass; it becomes the principal centre where price is formed and liquidity is consolidated.
This centralised structure directly affects the price formation mechanism. Price is determined by the balance of orders and transaction volume within the platform. Order intensity and liquidity levels become decisive factors in price formation. However, the fact that each platform establishes its own liquidity pool leads to a departure from a single, unified price structure. As a result, price formation acquires a platform-specific character, with each platform generating prices within its own internal dynamics.
At the same time, the concentration of transaction flow within a single system significantly enhances surveillance capacity. Order movements, volume changes, and anomalous behaviours can be analysed within a unified data set. The preservation of data integrity enables faster detection of abnormal market movements. This allows for continuous and effective monitoring of market behaviour.
When all these elements are considered together, the resulting model is clear: the market operates through a platform-centric structure rather than a dispersed order flow. Orders, liquidity, price formation, and surveillance functions are integrated within the same system, and transaction flow is organised within a centralised structure.
This structural choice directly impacts the overall functioning of the market. Each platform maintaining its own order book and liquidity structure leads to price discrepancies across platforms. Liquidity does not accumulate at a single point but is distributed across different platforms. This results in a multi-centred market structure.
The positioning of the platform as a structure that establishes the trading environment, executes transactions, and simultaneously monitors them—and, in certain cases, acts as a counterparty—creates a need for a delicate internal balance. Accordingly, the effectiveness of surveillance mechanisms becomes a structural element directly linked to market confidence.
Within this framework, the regulation should be understood as a clear structural preference regarding how the crypto-asset market is intended to operate.
Article 10 focuses less on what the platform does and more on how transactions flow within it. It reveals where order flow begins, how it is matched, and within which structure it is concluded.
The first paragraph defines the platform as a structure that manages the entire transaction chain. Orders are received, matched, executed, and assets are held. The platform assumes an active role at every stage of this process. This approach represents the consolidation of functions that operate separately in traditional markets within a single structure. Order flow begins on the platform, circulates within it, and is concluded within the same structure.
The second paragraph determines the rules governing this flow. The order execution policy defines how matching is carried out and which priorities apply. This policy establishes a technical framework that directly influences price formation. The transfer of cash balances to a bank on the same day limits price-related risk and reduces the platform’s balance sheet exposure. The segregation of client assets ensures that the internal record-keeping system operates in an orderly and traceable manner. All transaction data is maintained on a client-specific basis within the platform.
The third paragraph incorporates peer-to-peer marketplaces into the same structure. Direct matching of orders between users does not eliminate the platform’s responsibility. As long as the trading environment belongs to the platform, the entire flow is assessed within the same system. This ensures that transaction discipline is established through the platform, regardless of the source of the order flow.
The fourth paragraph introduces lock-up based transactions into the system. User assets are locked for a specified period and returned at maturity. This structure removes a portion of liquidity from circulation and creates a separate yield layer within the platform. Since locked assets are not part of active order flow, they directly affect instantaneous market liquidity.
The fifth paragraph recognises the role of liquidity provision and market making. The platform is no longer merely a matching mechanism; it directly participates in the market by quoting bid and ask prices. This represents active participation in price formation. Liquidity depth increases, transaction continuity is ensured, and the spread structure is shaped within the platform.
The sixth paragraph excludes certain asset types from this structure. Unique digital assets and in-game assets are treated separately. This distinction clarifies the scope of the market structure.
The seventh paragraph clarifies that entities which only provide quotes and supply liquidity are not considered platforms. These actors are positioned as market participants. The boundary between the platform and market players is thus clearly drawn.
The platform operates as a transaction centre that aggregates order flow, manages matching, acts as a counterparty when necessary, and retains liquidity within its structure. Market dynamics are shaped around this centre, and price formation occurs directly through it.
Article 10 establishes the structure in which order flow is concentrated. Article 11 defines the environment in which this flow operates and how liquidity is connected. When read together, these provisions demonstrate that the platform is not merely a structure that aggregates orders, but also a centre that establishes the trading environment and manages liquidity within it.
The first paragraph defines the core of the trading environment. Orders are matched within the platform. Matching is not limited to internal orders but may also occur through liquidity providers offering continuous bid and ask prices. This creates a hybrid model in which order book and quote-driven systems operate together. The platform both matches orders and connects external liquidity to the system.
The second paragraph opens the trading environment to international liquidity. Foreign institutions and their clients may directly submit orders to the platform. This expands the liquidity pool and ties price formation to a deeper data set. Order flow extends beyond local boundaries, and the market operates with global participation.
The third paragraph establishes the discipline governing this expansion. All incoming external order flow is integrated into the platform’s compliance framework. Customer due diligence, transaction monitoring, and financial crime controls apply equally to foreign-sourced transactions. Thus, while liquidity becomes global, control remains within the platform.
The fourth paragraph requires that external liquidity be governed by contractual arrangements. The relationship between the platform and liquidity providers becomes transparent. The nature of services and assets involved is clearly defined. This limits informal liquidity flows and ensures that all connections operate within a defined framework.
The fifth paragraph allows the platform to submit orders into its own trading environment. Within defined rules, the platform may contribute its own liquidity. This transforms the platform from a purely operational structure into an active market participant. The connection between order flow and price formation is thereby strengthened.
The sixth paragraph demonstrates that the trading environment is not limited to a single-layer structure. Platforms may establish different markets for different assets and investor profiles. Each market has its own trading rules, liquidity structure, and price formation dynamics. This allows multiple sub-markets to operate within the same platform.
The platform evolves beyond a centre that aggregates orders; it establishes an infrastructure that connects liquidity, shapes price, and creates layered market structures. Orders move within this system, liquidity concentrates within it, and price formation occurs directly through it.
While Articles 10 and 11 establish the structure of order flow and the trading environment, Article 12 introduces a third dimension: the platform directly entering into transactions as a counterparty.
The first paragraph allows the platform to fulfil orders outside the order book. The platform may execute client orders from its own inventory. In this case, the transaction is not matched through the order book but executed against the platform’s own balance sheet. In market terminology, this corresponds to “principal trading” or a “dealing desk” model.
Within this structure, the platform ceases to be merely a matching system and becomes an active counterparty. When the client buys, the platform sells; when the client sells, the platform buys. Transactions are executed directly through the platform’s balance sheet.
The same paragraph makes the economic consequence explicit. The platform may generate revenue when client positions close at a loss. This creates a direct link between transaction flow and platform profitability. Accordingly, clients must be clearly informed that the platform may act as counterparty. Transparency becomes a fundamental element of this model.
The second paragraph defines the limits of this structure. The platform may only take positions up to the amount of assets held in its own wallet. This prevents unlimited risk-taking beyond its inventory. Transaction volume is thus constrained by the platform’s holdings.
This reflects a controlled application of an “inventory-based trading” model. The platform trades using its own assets and does not create positions beyond its holdings. Market risk is therefore contained within defined limits on the platform’s balance sheet.
The netting mechanism further regulates end-of-day risk management. At a specified time, balances arising from counterparty transactions are settled and accounts are balanced. This prevents the accumulation of open positions and limits balance sheet volatility.
The platform thus goes beyond managing order flow and establishing the trading environment; it may also directly participate in the market using its own balance sheet. Liquidity is not solely derived from user orders; the platform’s inventory becomes part of the flow. Price formation is shaped by the interaction of these two sources.
This structure integrates order-driven and inventory-based trading models within a single system. The platform both establishes the market environment and participates in it. Market dynamics emerge from the interaction of these functions.
Article 10 concentrates order flow, Article 11 establishes the trading environment, and Article 12 positions the platform as a counterparty. Article 13 introduces the final balancing element: price surveillance.
The first paragraph defines the institutional structure of surveillance. A dedicated surveillance unit is established within the platform and operates in coordination with the risk management function. This creates a continuous control mechanism that monitors transaction flow from both technical and risk perspectives. Market movements, order behaviour, and price changes are tracked in real time.
The second paragraph sets out what is monitored and how action is taken. Transactions that cannot be justified on economic grounds are identified. Order concentrations, price spikes, volume anomalies, and similar behaviours are analysed. Findings are reported to senior management. The platform may intervene directly by restricting accounts, halting transactions, or closing positions. Such activities are also reported to the regulatory authority.
This establishes what is known in market terminology as a “surveillance layer.” Because order flow and price formation occur within a single centre, abnormal movements can be detected more rapidly and systematically. The platform becomes not only a trading venue but also a control point that continuously monitors and influences market behaviour.
The third paragraph formalises the operational framework of this system. Analytical tools, monitoring methods, intervention thresholds, and measures are predefined. This standardises surveillance processes and ensures consistency in platform operations.
The fourth paragraph introduces a differentiated approach for assets whose prices are formed in external markets. For assets traded extensively on international markets, the impact of internal surveillance mechanisms is limited. Price dynamics are determined by external liquidity and transaction volume. In such cases, the platform acts as a price taker rather than a price maker.
The platform thus incorporates a continuously operating surveillance layer on top of its trading and liquidity functions. Price formation, liquidity flow, and transaction behaviour are monitored within this layer. Market discipline is ensured not only through rules but through real-time data analysis and intervention capacity.
The platform simultaneously performs three core functions: it aggregates order flow, manages liquidity, and monitors price movements. The market is shaped through the interaction of these functions.
Articles 10 to 13 of Communiqué No. III-35/B.2 contain provisions that directly shape market functioning. The platform is positioned as the locus of transaction flow, the venue of price formation, and the centre of liquidity aggregation. The market is organised around this structure, and transaction dynamics are determined through it.